Keeping the vintage dress local

Early one Tuesday morning, I dropped books off at the library and continued on Denver Avenue.  But wait! I screeched to a stop. Is that my dress on display in the window of an antique shop?  I wheeled my bike over for another look.   It is!  That lovely grey and pink lace covered dress was my go-to fancy dress for years.  In fact, here’s a photo of me wearing it.

Riding the rest of the way to work, I tried to remember what happened to it. I’m pretty sure I donated it to the Goodwill.  But it’s made its way back to this vintage store.  We’re keeping it in the Kenton neighborhood.

Three sentence movie reviews: Free Ride

What happens when women make a movie about the drug trade? There’s a lot less on the action/adventure front and a lot more of the personal relationships. This was clearly a labor of love for all involved* and I really enjoyed this story, which probably could be told a thousand times over in different ways.

Cost: free from library
Where watched: at home

*Interestingly, the 70s classic rock song “Free Ride” by the Edgar Winter Group is not featured anywhere in this movie.  I’m assuming it’s because the rights were too expensive.

poster from: http://www.impawards.com/2017/free_ride.html

The imbalance of power

There are a lot of words being written about Harvey Weinstein.  A lot of people are having to check if he’s an E-I Weinstein or an I-E Wienstein.  I think this photo sums up the overall problem, in Hollywood, and in general. The woman on the right is Weinstein’s wife. She’s 41, and looks great. Because ultimately, that is women’s job in this world: to look pretty, to keep their figure, to be the sex object. In contrast, Harvey Weinstein is 65 and looks like crap.  Because it’s not his job to look good.  Instead, he gets to make a lot of money and acquire certain things: a successful movie producing company, willing to pay to settle multiple harassment cases with seemingly no penalty to him; plus a good-looking wife young enough to be his daughter.

I can’t know the specifics of the relationship of the two people pictured. But I know that finding a counter example–a couple consisting of a shlubby female successful 65-year-old business mogul* and an attractive 41-year-old man–would be tough enough that they would probably be the exception that proves the rule. Because men still run the show in this country.  And what a lot of them chose to do with their power is exploit other women, elevate men like them who won’t rock the boat, and keep women in their place.

(*Because 65-year-old female business moguls are few and far between and the ones who do exist are decidedly not schlubby. Because: not allowed.)

Hollywood and the media’s focus on style over substance magnifies this situation, but it exists in every corner of our society.  Things are changing, but not fast enough.

One Story: Toby and A Month on Greene Street

A story of loss, written by a student at Portland’s own Grant High School.

Tom Hanks has a successful career as an actor, director and producer. Plus a book deal for his short stories. He’s probably got enough money to start his own literary magazine.  Thus, it bugs me that he’s taking up space in the One Story lineup.  That said, I quite enjoyed this story.

Debt Repayment Calculator

Accelerating payments is kind of boring.  It’s a lot of cutting back on this and that on a daily basis, and then eventually, once per month, you have something to get excited about: WHAMMO! Extra payment.

But here we are early in the month, with September’s extra payment made and all of October left to go.

Today I found a Debt Repayment calculator that cheered me a little.  The one I used is very no-frills and is found at Debt Repayment Calculator. The site even says in the upper left hand corner “You can deal with it” and has a very calming rainbow/banner thing.

I typed in my amount of debt, my interest rate and my current monthly payment. Then I added an additional monthly payment of $500 and the site told me that if I just made my monthly payments I would be paying this loan off for 72 more months and would pay an additional $543.14 in interest.

But!  If I make an extra payment of $500/month for 12 months, all of my student loan debt will be GONE!  Twelve months! So exciting!  Then I can put all that money into savings/investing and retirement.

That’s good news!

Payoff! October report

Much to report this month!  I made a big decision.

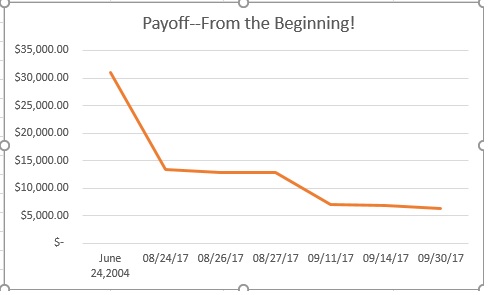
What I paid toward the loan in September. $6567.25.  That includes my regular payment of $189.37, plus a payment of $5852.00, plus an end-of-the-month payment of $525.88.

How much I paid toward the principal and how much toward the interest. Principal: $6567.25. Interest: $23.20.

Where the money for my extra payments came from.  I had a $10,000 emergency fund, a goal I finally achieved right before my 40th birthday. It was depleted by about 20% this year when I learned that my health insurance that my employer pays $485 per month for doesn’t really cover that much.  I had been focusing my efforts on getting money back into that fund.  But looking at my loan balance, I saw that there were two loans, one for $5k+ and one for $7k+.  What if I paid off the $5k+ totally?  On the one hand, that would deplete my emergency fund down to a little over one month’s cushion.  On the other hand, I could totally eliminate one part of my debt.  I eventually decided to do it, as you can tell from the above numbers.  My rational is that my job feels pretty secure (knock on wood) and the amount of interest my savings account is paying is far less than the interest on this loan. Plus, the psychological boost.  So I did it.  I had to write the loan company to find out how to apply the entire chunk only to one loan.  It turned out to be easy.  I made the payment, and then sent a message to apply all of the payment to the loan in the amount of $X.  Boom!  When you look at my loan list, that loan is gone.

In addition, at the end of the month, I added to my budgeted amount ($324.07) another $201.81.  That came from my unused Dining Out money ($40.00–all of my eating out in September was paid for by my company, or by a friend as thanks for resume help) and also my unused grocery money ($49.81). I made two lifestyle changes this month.  One was I decided to stop taking tap dance lessons.  I’ve been feeling too busy during the week for a while now, but had made a stink about having an Intermediate Level Tap class, so then had to take the lessons.  At the time, they were running the class with only two people total, so I kept going because I liked it, but also because I didn’t want to be the person who made the stink and then didn’t sign up. There are a few more people in the class now, so I feel like I can take a break.

Also, TriMet now allows you to buy the amount of train fare you need for the month.  I figured if I could ride my bike one day per week, and then also walk one way one day per week, I could pay less than $100/month.  My company reimburses for transportation, phone and internet up to $100/month, so this month I submitted my phone bill along with my TriMet fare purchase and netted an extra $29.50 to put toward this goal.  We shall see how this biking to work and walking once per week goes.  I’m feeling excited about it now, but I was pretty burnt out biking to my previous job. Though that was every day.  Also I wasn’t necessarily choosing it.  I wasn’t really paid enough to afford to bus to work.  (Thank goodness that job is over!)

A list of what I didn’t buy in order to put more money toward this project. To sum up: most of my emergency fund; tap dance class; full monthly TriMet pass.

Any roadblocks I’m having toward this goal.  I’m worried that this will become a tedious, sad task after this month.  I’m down to less than $6k, but I feel as though I have plucked all the low-hanging fruit. I can’t just decide in October to pay the rest off in one fell swoop, because I don’t have another $6k hanging around. Hopefully this will not be the case.  If so, I will have to figure a plan.

Here’s what things looked like at the end of August:
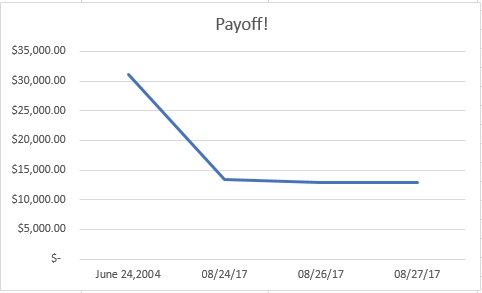
And here’s the graph at the end of September: