Thrift Food Plan report October 2017

It’s like the newspaper reads my blog! Here’s an article published about the amazing deals to be had at WinCo.
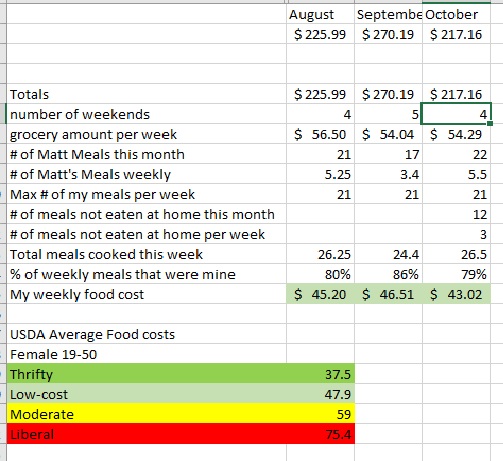
Well darn it, despite being careful all month, I did not meet my goal of my weekly groceries averaging out to be $37.50 (or lower).  In good news, my weekly food costs, were $43.02, which was a new low.  And they were lower than August and September by  $2.18 and $3.49 respectively.  I’m still spending less than the low-cost food plan.
In order to have met my goal, I would have had to shave $22.08 off my grocery bill.  One thing that may have got in the way was making two birthday cakes.  I had to buy honey from New Seasons, rather than WinCo, and that cost $10.00.  It would have been cheaper if I planned ahead.  Also, I bought bulk sliced almonds to decorate the outside of one cake and then nearly had a heart attack when I looked at the receipt and noticed they were $5.50.  I have both leftover honey, which will go to bread making, and almonds, which will be used for a meal this week.

I think the other thing that would help is if I wouldn’t cook from recipes so much, as that usually results in having to buy random things I wouldn’t usually purchase. But I find that without a recipe, my food becomes very bland, as I’m not well versed on improvising spices.

I have been substituting ingredients to ones I have on hand.   I have a delicious bean and cheese pie recipe that called for one can pinto beans and one can garbanzo beans.  I had on had two jars of frozen pinto beans, so I used them instead and the resulting dish was delicous.

On the last weekend of the month, I bought ingredients for “inside out stuffed pepper soup” which called for both ground beef and Italian sausage, plus a red bell pepper.  All of those ingredients are spendy.  I would have been better off sticking to a bean soup for this last weekend of shopping.  The previous week I had too much celery and I googled “celery and bean soup” which gave me this amazing recipe.  I marveled that an onion, celery, beans and salt could end up tasting that good.  Although, I had to buy white beans at Fred Meyer (more expensive) because I didn’t buy any on my monthly WinCo shopping trip.  They will be on the November WinCo shopping list.

On the plus side, I cooked 22 meals for Matt this month, which gives me a tidy $90.20 payment from him.

November will bring its own challenges with Thanksgiving, so I will think of ways to make that holiday affordable.  I see why employees used to get hams and turkeys as presents around the holidays.
Debt Repayment Calculator

Accelerating payments is kind of boring.  It’s a lot of cutting back on this and that on a daily basis, and then eventually, once per month, you have something to get excited about: WHAMMO! Extra payment.

But here we are early in the month, with September’s extra payment made and all of October left to go.

Today I found a Debt Repayment calculator that cheered me a little.  The one I used is very no-frills and is found at Debt Repayment Calculator. The site even says in the upper left hand corner “You can deal with it” and has a very calming rainbow/banner thing.

I typed in my amount of debt, my interest rate and my current monthly payment. Then I added an additional monthly payment of $500 and the site told me that if I just made my monthly payments I would be paying this loan off for 72 more months and would pay an additional $543.14 in interest.

But!  If I make an extra payment of $500/month for 12 months, all of my student loan debt will be GONE!  Twelve months! So exciting!  Then I can put all that money into savings/investing and retirement.

That’s good news!

Payoff! October report

Much to report this month!  I made a big decision.

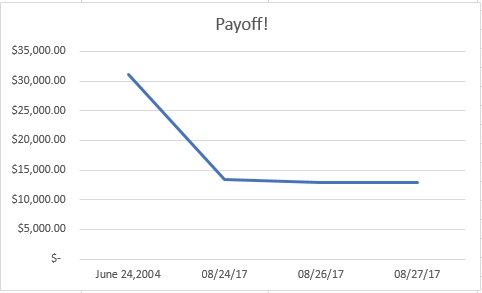
What I paid toward the loan in September. $6567.25.  That includes my regular payment of $189.37, plus a payment of $5852.00, plus an end-of-the-month payment of $525.88.

How much I paid toward the principal and how much toward the interest. Principal: $6567.25. Interest: $23.20.

Where the money for my extra payments came from.  I had a $10,000 emergency fund, a goal I finally achieved right before my 40th birthday. It was depleted by about 20% this year when I learned that my health insurance that my employer pays $485 per month for doesn’t really cover that much.  I had been focusing my efforts on getting money back into that fund.  But looking at my loan balance, I saw that there were two loans, one for $5k+ and one for $7k+.  What if I paid off the $5k+ totally?  On the one hand, that would deplete my emergency fund down to a little over one month’s cushion.  On the other hand, I could totally eliminate one part of my debt.  I eventually decided to do it, as you can tell from the above numbers.  My rational is that my job feels pretty secure (knock on wood) and the amount of interest my savings account is paying is far less than the interest on this loan. Plus, the psychological boost.  So I did it.  I had to write the loan company to find out how to apply the entire chunk only to one loan.  It turned out to be easy.  I made the payment, and then sent a message to apply all of the payment to the loan in the amount of $X.  Boom!  When you look at my loan list, that loan is gone.

In addition, at the end of the month, I added to my budgeted amount ($324.07) another $201.81.  That came from my unused Dining Out money ($40.00–all of my eating out in September was paid for by my company, or by a friend as thanks for resume help) and also my unused grocery money ($49.81). I made two lifestyle changes this month.  One was I decided to stop taking tap dance lessons.  I’ve been feeling too busy during the week for a while now, but had made a stink about having an Intermediate Level Tap class, so then had to take the lessons.  At the time, they were running the class with only two people total, so I kept going because I liked it, but also because I didn’t want to be the person who made the stink and then didn’t sign up. There are a few more people in the class now, so I feel like I can take a break.

Also, TriMet now allows you to buy the amount of train fare you need for the month.  I figured if I could ride my bike one day per week, and then also walk one way one day per week, I could pay less than $100/month.  My company reimburses for transportation, phone and internet up to $100/month, so this month I submitted my phone bill along with my TriMet fare purchase and netted an extra $29.50 to put toward this goal.  We shall see how this biking to work and walking once per week goes.  I’m feeling excited about it now, but I was pretty burnt out biking to my previous job. Though that was every day.  Also I wasn’t necessarily choosing it.  I wasn’t really paid enough to afford to bus to work.  (Thank goodness that job is over!)

A list of what I didn’t buy in order to put more money toward this project. To sum up: most of my emergency fund; tap dance class; full monthly TriMet pass.

Any roadblocks I’m having toward this goal.  I’m worried that this will become a tedious, sad task after this month.  I’m down to less than $6k, but I feel as though I have plucked all the low-hanging fruit. I can’t just decide in October to pay the rest off in one fell swoop, because I don’t have another $6k hanging around. Hopefully this will not be the case.  If so, I will have to figure a plan.

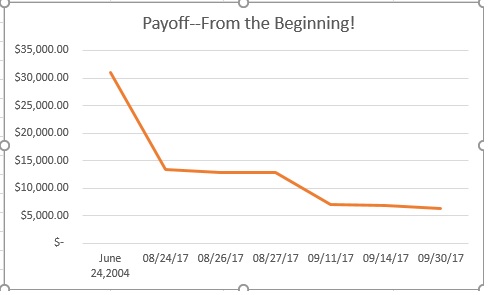
Here’s what things looked like at the end of August:

And here’s the graph at the end of September:

Challenge. Me, the food I eat, and the USDA Thrifty Food Plan

In looking for ways to send more of my money toward the payoff of my student loan, I’m going to focus on reducing my food costs in the last three months of 2017

There are many different ways to look at food costs.  Some people lump their grocery and eating out budgets into one line.  Some people look at the amount for the entire month, while others look at their food budget weekly. Some people even will break down each meal into a cost.

I have a couple of complicating factors in tracking my grocery bill.  One has to do with the calendar.  There are 30 days in some months, 31 in others.  Some months have four weekends, some have five.  Also, I make and sell meals to Matt.  This came about because I needed a side job, and one of my skills is cooking. He has no desire to develop that skill in himself (thus far) and needed to reduce food costs.   This has been great for both of us.  For me, it’s easier to make recipes that feed more than one person.  Plus, I get a little extra cash on the side.  Matt gets a variety of nutritious food for less than he would pay eating out.  I charge him $4.10 per meal.

A few years ago, I was searching the internet to find out what is a reasonable amount to spend on groceries.  I discovered the USDA’s Food Plans.  In a delightful bit of government minutia, food costs are tracked monthly and published on the USDA website. In one handy PDF document, you get food costs broken down by age, gender and family. Plus you can see the average cost under four USDA plans broken down weekly or monthly.

Example: For August 2017, a female between the ages of 19 and 50 would find the weekly/monthly Thrifty Food Plan costs to be $37.90/$164.20; the Low-Cost Plan to be $47.90/$207.50; the Moderate-Cost Plan to be $59.00/$255.80; and the Liberal Plan to be $75.40/$326.70.  Note that these plans assume all meals and snacks for the week/month are prepared at home.

This is super cool and gives me a goal.  Except, I also have to somehow reflect the fact that 4-6 meals worth of food per week go to a male between the ages of 19-50 years old (Thrifty food cost for that category is $42.80/$185.40).  What to do, what to do?

I went back and crunched my grocery numbers from YNAB. There’s a whole spreadsheet, but I won’t make you read that. I’ll just sum up what I found.

First of all, I decided that the grocery shopping week begins on Saturday.  I do my shopping on Saturday or Sunday.  Thus, months that have five weekends, the total monthly food cost gets divided by 5. (Of course, October is the rare unicorn and begins on a Sunday, making things complex. I gave September 5 weekends, and October 4)

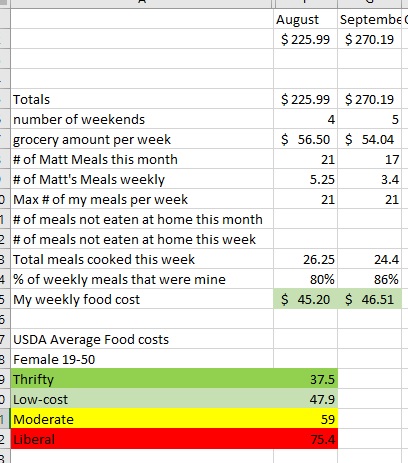
From April through September my average weekly food costs were $64.97 which puts me above the Moderate and below the Liberal Plan. Drat!  Although August & September took a deep dive with $56.50 and $54.04 weekly totals.

But! Some of those food costs went to meals for the 19-50 year-old male.  I don’t have data prior to August, but in August I sold Matt 21 meals and in September there were 17. (Vacation happened.)

I took the average number of Matt’s meals per week and added them to the total number of meals per week for me (7 days times 3 meals per day gives me 21 per week) giving me a total of 26.25 meals per week in August.

After that, I figured out what the weekly percentage was for my meals.  In August  that was 80%.  Using that percentage, I could then calculate my actual average weekly meal costs.  My total:  $45.20 which puts me below the $47.90 Low-cost plan but not reaching the threshold of $37.90 Thrifty food plan.

I’ve realized there is a slight flaw in my data in that I don’t actually know how many meals I ate in the month.  As mentioned before, vacation happened and the food budget for vacation happens outside of this grocery budget.  I also don’t know how much I ate out in August, or September. Though my $40 eating out budget remained untouched all month (good job, me)a friend did buy me lunch for helping her with her resume.  Plus work bought at least two lunches.

I have added lines to my spreadsheet so I can more accurately reflect the number of days I ate meals that I prepared.

My goal for October, November, December is to meet the Thrifty Plan Food costs while still eating a variety of delicious food with a lot of fruits and vegetables.  I still plan to buy my red meat and poultry at New Seasons, which costs more, but I hope to offset that by doing the bulk of my shopping once per month at Winco (I have rediscovered the amazing deals) and cooking more with low-cost ingredients as well as using meat and cheese as flavor enhancers and not the main event.  I will also figure out a way to better ascertain if Imperfect Produce is a good enough deal to keep going with.

Right now, I’m pleased that my grocery costs are in the Low-Cost range.  But the monthly difference between the Low-Cost and Thrifty plans is $43.30.  Over one year that is $519.60 that would be better off being paid toward my student loans.

Orange Door Project: Side Yard rehab

Project time!  We are making a nice path from the sidewalk to the edge of the backyard.  I look forward to not walking through mud (in the winter) weeds (in the summer) and cat poop (year round.)

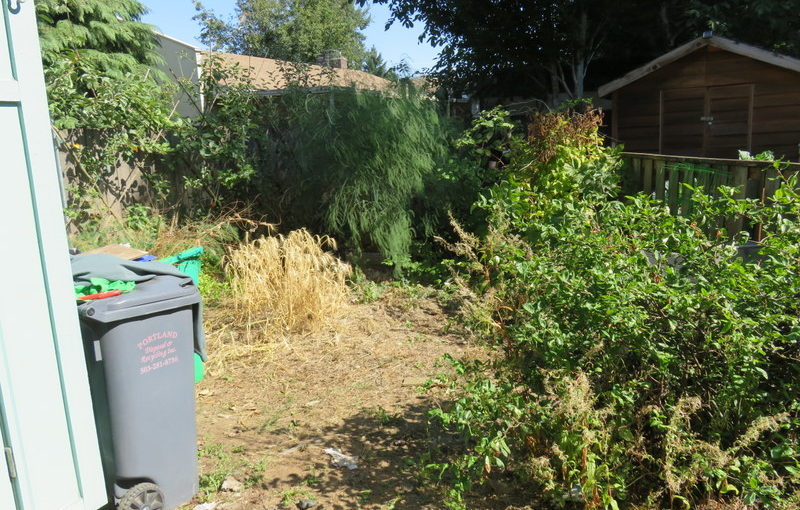
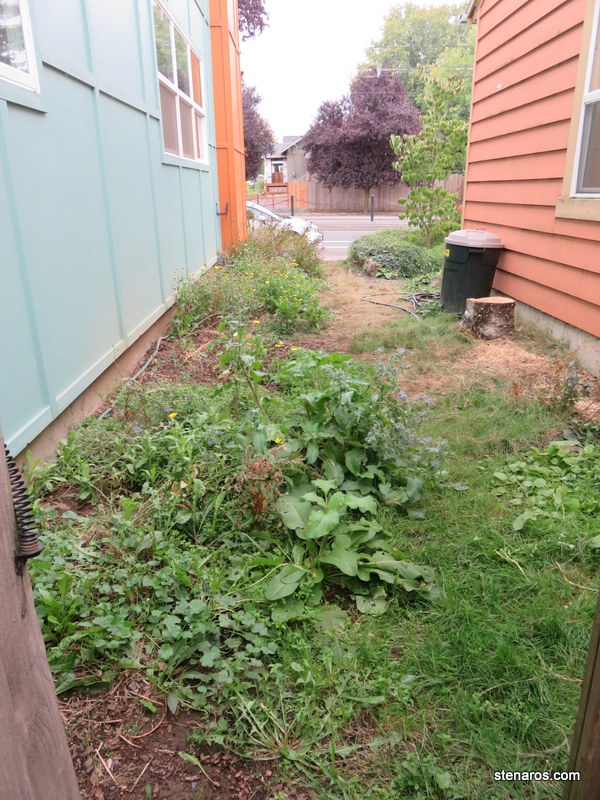
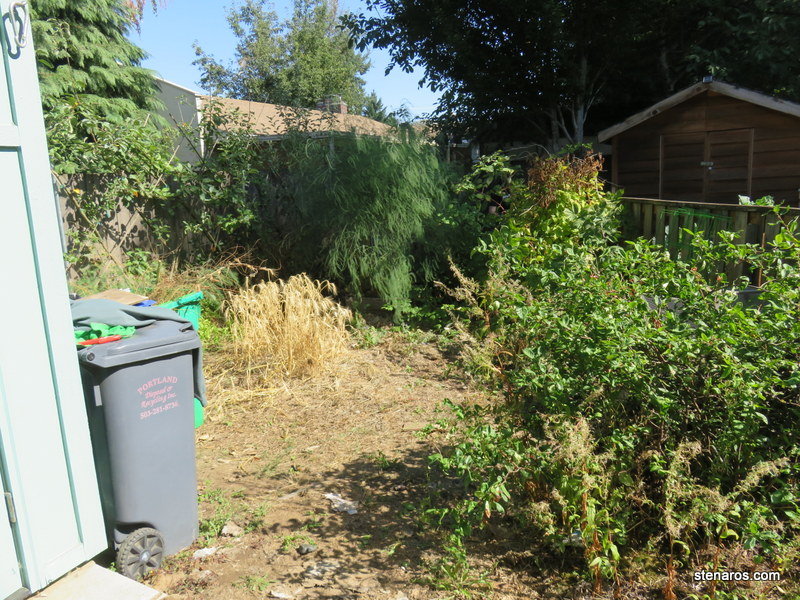
Here are our “before” photos.  Side yard from the fence to the edge of the yard.  Big weedy mess. 

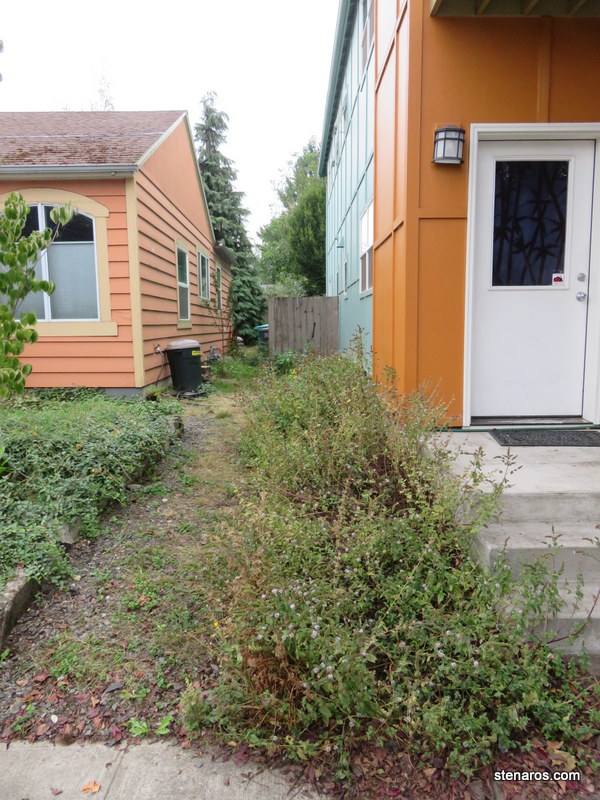
From the fence to the sidewalk: big weedy mess.

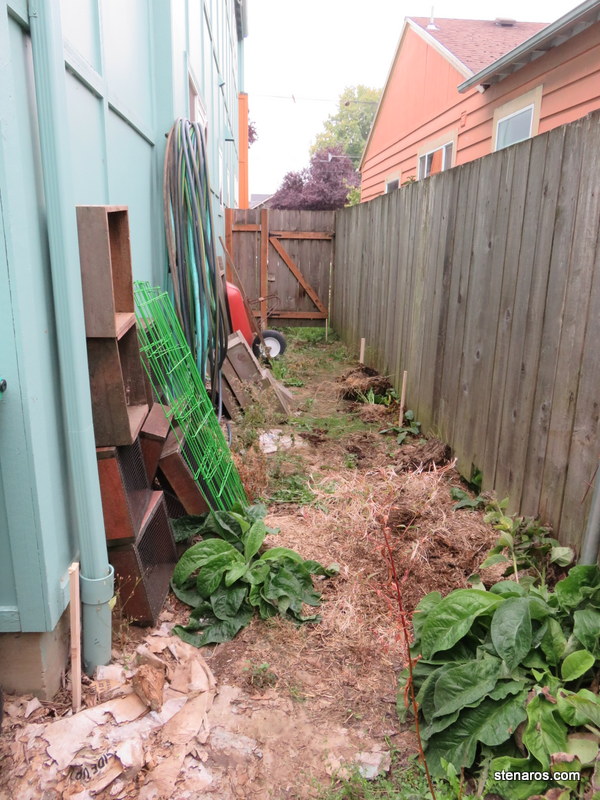
From the sidewalk looking back to the fence:  big weedy mess, though that is mint that I planted.

The side yard is a Fall 2017 project. After that, we will tackle the backyard, which is a Spring 2018 project.

The plan for the side yard: clear all the vegetation, dig out 4″ of dirt.  Add back in 2″ of gravel, landscape cloth, a layer of sand, flagstone, then more gravel.  I’m very excited to be done with this project and have an easy  passage.

Day of Projects

Today was a day to get things done.  And I did!

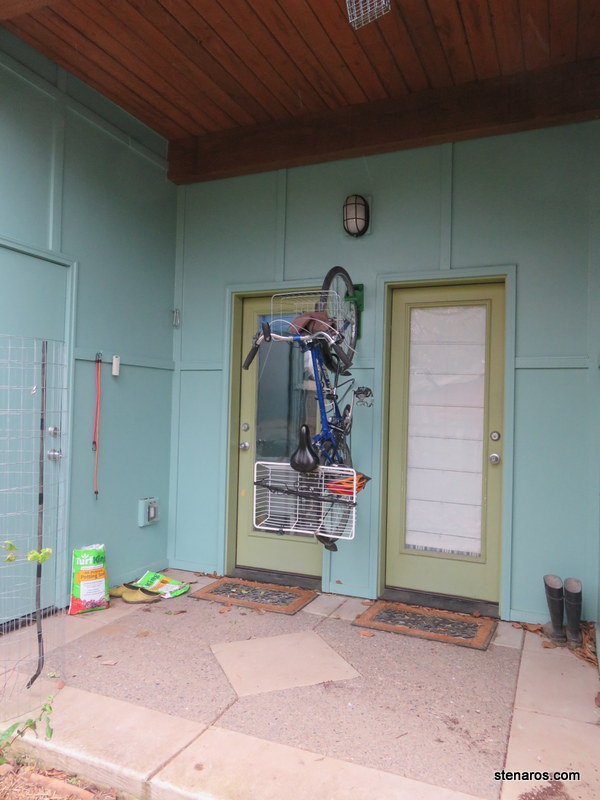
I hung the first of two bike hangers on the back porch.  This gets my bike out of our laundry/pantry area.  We have plans to also hang Matt’s bike from above.  But the ladder in combination with my height was not tall enough to do that project, so that will have to wait until Matt is home.

This picture shows off what part of the paint job didn’t get done.  This summer, when they repainted our house, they did not paint the surrounds around the doors, or the doors.  I’ve got it on the project list, but I don’t know if it will ever get done because I hate painting.  Also because anything with doors means leaving the doors open until the paint dries. Which is more complicated with the cats.

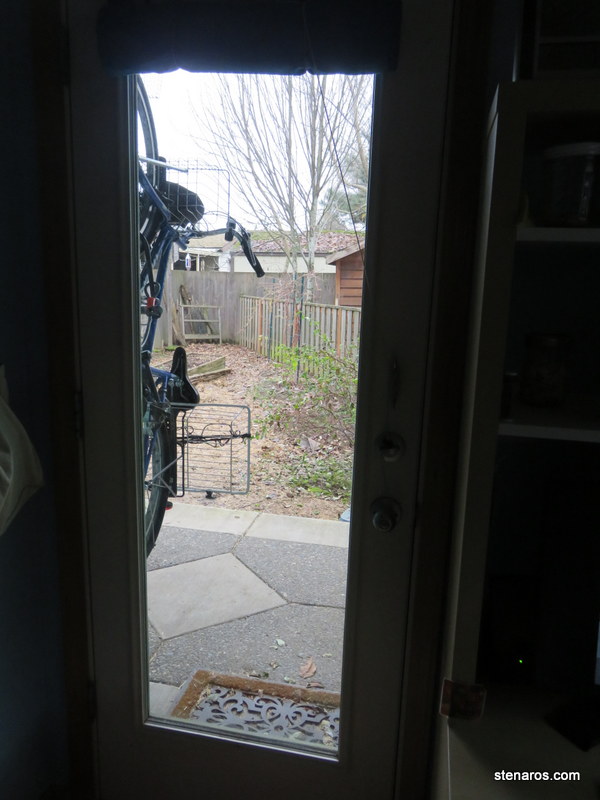
The new bike changes the view from my desk. 

Now I just have to put the pantry in order.

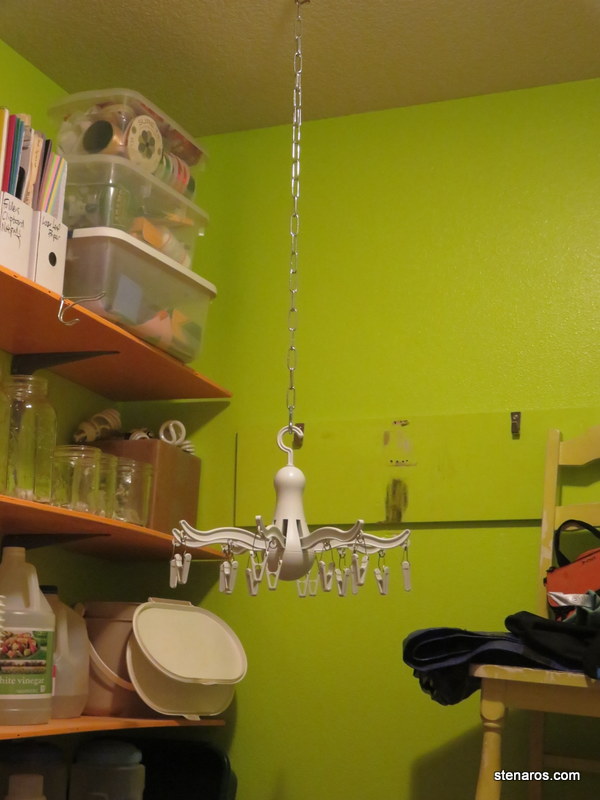
I took this octopus hanger out of the closet and put it closer to the washer.  I will hang my washcloths from it.

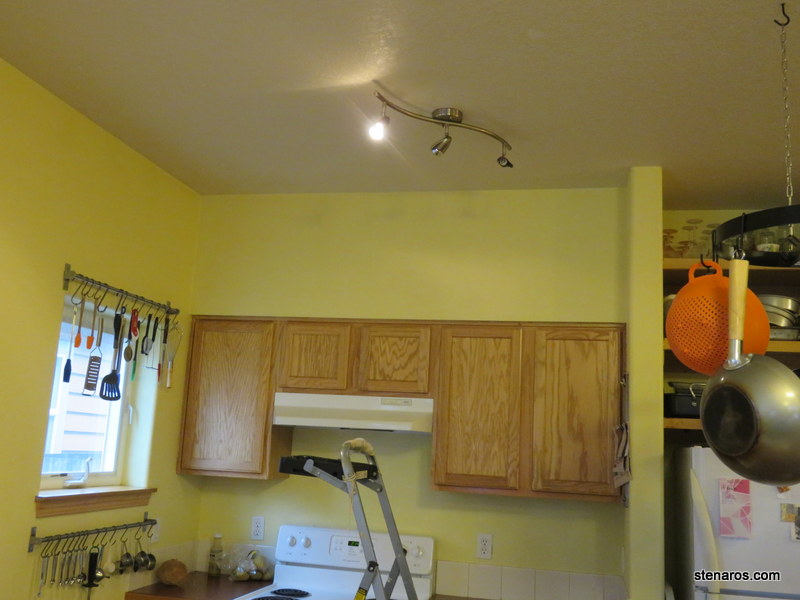
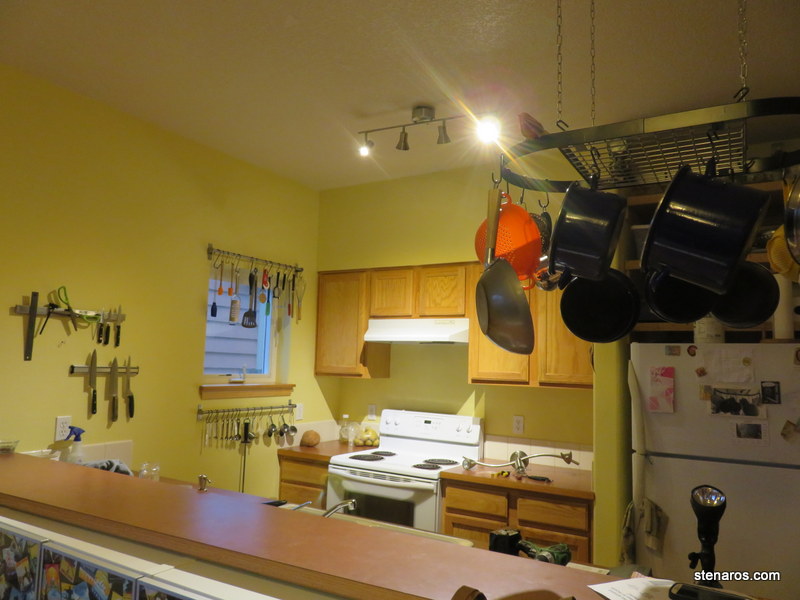
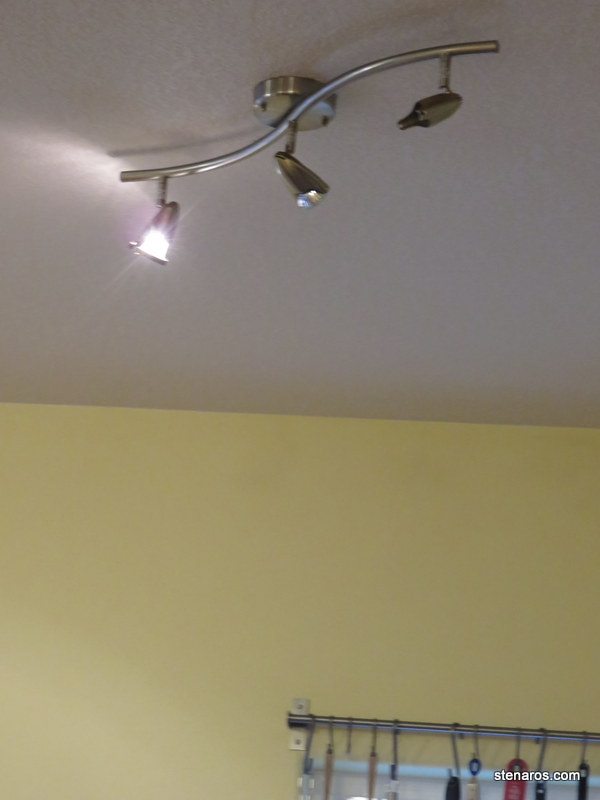
Our kitchen light wasn’t working.  We were down to one working light in the fixture.  Time for a new kitchen light.

This is not the best picture, but here is the new fixture I installed.  I love that it has LED lights, so we don’t have to change them.  We also gained a light with the new fixture.  (Four instead of three.)

In the fashion of all projects, there was a trip to the hardware store.  I enjoyed coming across this truck, with an improvised–yet decorated–tailgate.

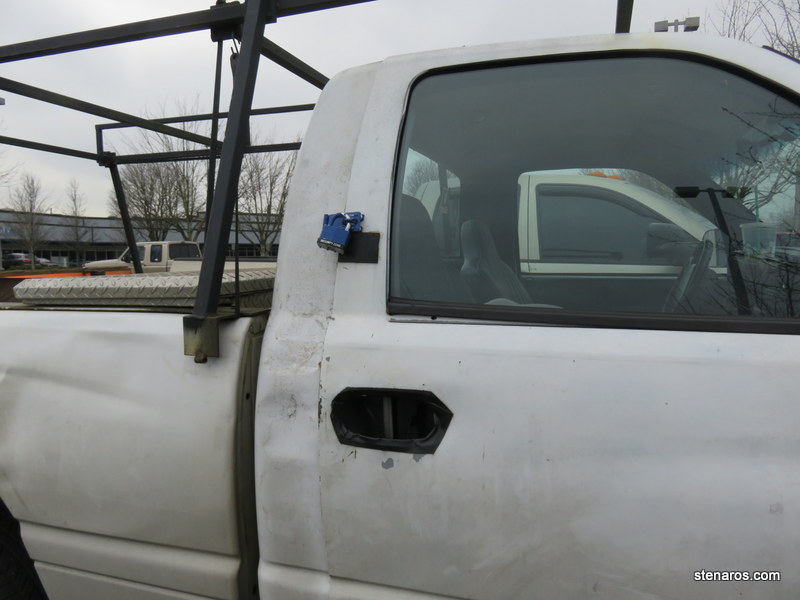
The same truck also had this improvised locking system.
It was a good day of projects.